BOFIT Forecast for China 2026–2028
2/2026, published 2 November 2026
China’s economic growth this year has outpaced most large economies, but the signs of slowing growth are evident and the structure of growth has become increasingly distorted. Domestic demand growth remains stagnant and the multi-year downturn in the real estate sector continues. At the same time, China’s economy has become even more dependent on exports, high-tech production and capital investment subsidised through industrial policy. Economic growth will continue to slow over the forecast period as domestic demand remains weak and the economy’s growth potential is limited by an ageing population and modest productivity gains. Despite new support measures introduced by government officials, China’s economic policies remain strongly focused on bolstering production and the country’s quest for technological self-sufficiency. Less priority has been given to improving the material well-being of households. This divergence in economic performance not only increases internal and external imbalances, but can further enflame trade tensions.

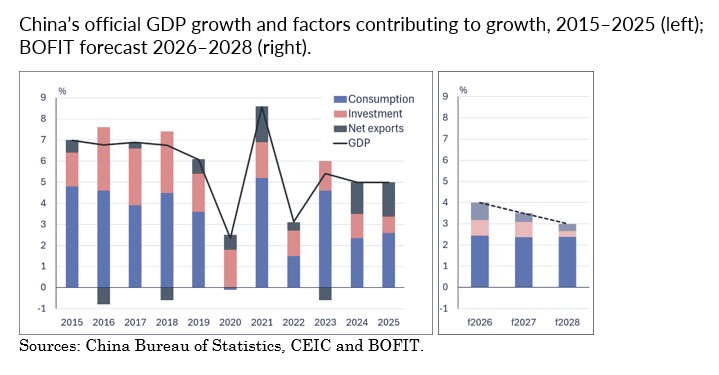
China’s economic growth has slowed over the course of 2026. While industrial output growth has remained strong, especially in high-tech sectors, domestic demand growth has been subdued. Chinese authorities are targeting GDP growth of 4.5–5 percent this year, and official figures are again expected to fall within the target range. However, the broader picture of economic activity suggests that actual growth is weaker than indicated by the official figures. We expect China’s GDP growth to come in at around 4 percent this year, followed by further slowing to around 3½ percent in 2027 and roughly 3 percent in 2028. The main factors dragging down growth are muted domestic demand, China’s rapidly ageing population, as well as the diminishing returns from its investment-driven growth model and low productivity growth.
Weak domestic demand persists
Chinese consumer confidence remains subdued. The decline in housing prices, now in its fifth year, is weighing on the willingness of households to consume, given that a significant share of household wealth is tied up in housing. Additionally, weak labour market conditions continue to discourage consumption, while the household savings rate remains high. The situation is particularly difficult for young people and recent university graduates. Uncertainty in the labour market encourages households to be cautious. Weak stock market performance this year has further impaired household wealth-building and the willingness of households to consume. Although officials have increased subsidies for families with small children and implemented a few targeted measures to support consumption, these actions are unlikely to substantially alter household behaviour. Thus, we expect the pace of consumption growth to remain moderate. Demand for services will provide some support, but there are no signs of a major shift towards consumer-driven growth.
Officials dealing with the ongoing correction in the real estate sector seem to have settled on a set of policy packages for stabilising the sector. China’s shrinking population, large stocks of unsold apartments and weak demand constrain the sector’s recovery. While we expect the decline in the real estate sector to ease somewhat over the forecast period, the sector can no longer be counted on as a significant source of growth. Growth in industrial capital investment has also slowed. The low capacity utilisation rates and weak corporate profitability in many industries will continue to reduce the need for new investment in the coming years.
Investment increasingly goes to industries that enjoy government priority. These industries include semiconductor manufacturing, robotics, electric vehicles, battery technology, renewable energy and the build-out of digital infrastructure. The expansion of the artificial intelligence (AI) sector supports production, but its impact on overall economic growth could be more limited than expected unless technological advances become more clearly reflected in productivity across the economy. The new Six Networks investment programme aims at extensive infrastructure investments in areas such as power grids, data centres, computing capacity, 6G networks and logistics. While these investments support economic growth and technological development, their ability to replace the real estate sector’s previous role as an engine of economic growth is limited. High-tech sectors are also less labour-intensive than average, so their impact on domestic demand may be smaller.
Importance of exports continues to grow
Exports have become an important pillar supporting economic growth in recent years. However, export growth has also become increasingly uneven, with a handful of high-tech industries accounting for much of the expansion. Exports of AI-related products, battery technology and electric vehicles have continued to grow strongly, while growth in more traditional industries has been considerably more subdued.
China’s export performance is supported by its large production capacity and firms’ strengthened technological capabilities. As a result, China boasts a strong position in several fast-growing technology sectors. Substantial industrial subsidies and a weak currency have also contributed to the strong competitiveness of Chinese exports. At the same time, China’s export success has increased geopolitical trade tensions and led to the erection of numerous trade barriers. US-China trade continues to be limited by high tariffs and technology restrictions, with some trade consequently being rerouted through third countries. EU-China trade tensions have also increased as China’s goods trade surplus continues to grow.
We expect exports to continue to rise throughout the forecast period, although the pace of growth should gradually fall towards that of global trade overall. China’s current account surplus will nevertheless remain large, implying that its external imbalances are unlikely to diminish significantly in coming years.
Fiscal and monetary policy support growth, but the policy space has narrowed
Chinese officials this autumn announced new targeted measures to support the economy. In particular, programmes related to infrastructure, technology and targeted lending have been expanded. Measures aimed at stabilising the housing market have also ramped up. Room for manoeuvre in fiscal policy, however, is limited by the rapid growth in China’s public debt. When debt held by local government financing vehicles is included, public debt rose to 127 % of GDP last year and is projected by the IMF to increase to 135 % this year. Local government finances are in a particularly dire situation as revenues from land sales have collapsed. Although the central government still has room to increase borrowing, current policy focus seems to be more on limiting the slowdown in economic growth rather than launching a strong stimulus response.
More significant monetary policy easing is limited by the fact that interest rates are already distinctly lower than in other major economies. Further interest rate cuts would weaken bank profitability and could impair their ability to lend. Pressure on capital outflows and yuan depreciation could increase, further exacerbating trade tensions. At present, the main constraint appears to be weak demand rather than the cost of financing.
Downside risks predominate
There are risks that economic growth will fall short of our base scenario. Problems in the real estate market, weakening local government finances and burgeoning bank credit risk could reinforce each other and tighten financial conditions. Tighter trade policies and increased geopolitical tensions could weaken China’s export outlook and slow growth. In addition, shortcomings in the statistical data and government censorship make it more difficult to assess the actual state of the Chinese economy.
On the upside, growth could also exceed our forecast if such measures as social security reforms strengthen consumer confidence or stabilisation of the real estate market occur sooner than expected. Faster and more substantial fiscal stimulus than assumed could also support growth.